TL;DR
- A digital banking platform handles customer channels, onboarding, payments, cards and integrations on top of the core banking system.
- Core banking keeps the books; in digital banking architecture the platform owns the customer experience, process orchestration and integrations.
- A platform has nine main components, from channels and an API gateway to security and notifications.
- Monolithic cores change slowly; a composable architecture releases, scales and replaces components independently.
- Microservices and an API-first design bring speed and isolation, and ask for mature DevOps in return.
- Cloud-native design adds containers, managed services, infrastructure as code and multi-AZ resilience.
- Zero trust, encryption, PCI DSS v4.0.1 and audit logging belong in the architecture, not on top of it.
- Moving off a legacy core works best in phases: an API layer first, then function-by-function migration.
Introduction
Banks and fintechs are moving from monolithic cores to modular architectures because old infrastructure cannot keep up with new products and integrations. The decisions made at the start set how fast you can ship features for years.
The cost of standing still is visible. More than 64% of banks’ global technology budget goes to maintaining legacy systems and only 36% to development or transformation, according to the Omdia Retail Banking Survey. At the same time the digital banking platform market is estimated at $14.85 billion in 2025 and is projected to reach $57.24 billion by 2035, a CAGR of 15.62%, per a Market Research Future press release.
This guide explains digital banking platform architecture: what a platform is, its components and features, how core banking architecture differs between monolithic and composable designs, what microservices and cloud-native design add, which technology stack fits, how to secure it and how to migrate.
What Is a Digital Banking Platform
So, what is a digital banking platform? It is a set of services that provides customer channels (mobile and web), onboarding, payments, cards and integrations on top of core banking.
Core banking is the accounting engine: accounts, the ledger, products and postings. The platform is built around it and exposes its capabilities through APIs. The split is simple: the core owns accounting and product rules, while the platform owns customer experience, process orchestration and integrations.
Digital Banking Platform Components
A typical set of digital banking platform components looks like this:
- Channels layer: mobile app, web, chatbot and partner integrations.
- API gateway and orchestration: a single entry point with routing, rate limiting and authentication.
- Core banking: accounts, ledger and product rules.
- Customer onboarding: KYC/AML, verification and scoring.
- Payments hub: internal and external transfers and integration with payment rails.
- Cards and wallets: card issuing, tokenization, Apple Pay and Google Pay.
- Data and analytics: a data store, reporting and ML models.
- Security and IAM: authentication, authorization and key management.
- Notification and communication service: push, SMS and email.
Digital Banking Platform Features
On the customer and back-office side, the main digital banking platform features are:
- Digital onboarding: opening an account without visiting a branch.
- Account and transaction management: balances, statements and payments.
- Card management: issuing, limits and blocking.
- Personal finance tools: spending categories and goals.
- Open banking APIs: access for third-party apps with customer consent.
- Admin and back-office tools: role-based access, case management and reporting.
Core Banking Architecture: Monolith vs Composable
Core banking architecture is where the biggest trade-off lives.
Banking Software Architecture: Layers and Patterns
Modern banking software architecture combines a few well-known patterns:
- Layered: presentation, API, business services and data.
- Event-driven: events (Kafka or similar) for payments, notifications, audit and keeping services in sync.
- API-first: every capability is available through an API, and all channels and partner integrations are built on it.
- BIAN and MACH: BIAN is an industry blueprint of bank service domains; MACH stands for Microservices, API-first, Cloud-native and Headless. MongoDB describes the shift toward composable systems.
Microservices Architecture in Banking
Microservices architecture in banking treats business domains as services. Our glossary has a short entry on microservices architecture if you need a refresher.
- Domains as services: accounts, payments, cards, onboarding and notifications deploy and scale independently.
- Upsides: faster releases, fault isolation and the ability to change one component without rewriting the core.
- Downsides: distributed transactions, harder observability and a need for a mature DevOps culture. See our entry on DevOps.
- Migration: a big-bang core replacement is giving way to phased, side-car approaches, where new services run next to the old core (Omdia).
Cloud-Native Banking Architecture
A cloud native banking architecture builds on cloud infrastructure and usually includes:
- Containers and orchestration: Kubernetes, autoscaling and self-healing.
- Managed services: databases, message queues and secret management.
- Infrastructure as Code: a reproducible environment and controlled change.
- Resilience: multi-AZ deployment, disaster recovery, monitoring and alerting.
- Regulation: data residency and digital operational resilience requirements (DORA in the EU).
Digital Banking Technology Stack
A digital banking technology stack typically looks like this. For the language question, see our comparison of Java vs Node.js in fintech scaling.
- Backend: Java or Kotlin, Node.js, .NET or Go with PostgreSQL.
- Messaging: Kafka or similar for event-driven communication, Redis for caching.
- Cloud and infrastructure: AWS, Azure or Google Cloud, Kubernetes and Terraform.
- Frontend: React or Next.js for web, React Native or native for mobile.
- Security: OAuth 2.0 and OpenID Connect, mTLS, KMS or HSM for keys.
Banking System Architecture Diagram
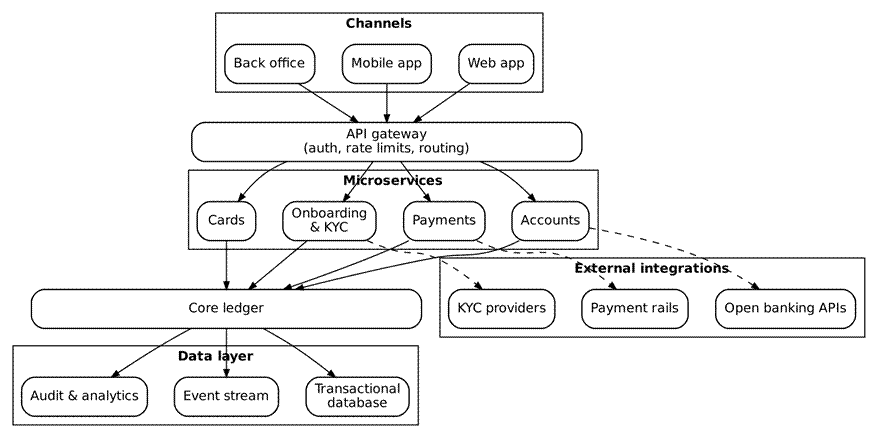
The diagram below shows how the pieces connect: channels, then the API gateway, then microservices, the core ledger and the data layer, with external integrations at the side.
Security and Compliance in Banking Architecture
- Zero trust: every request is authenticated and authorized regardless of network perimeter.
- Encryption: TLS in transit, AES-256 at rest and key management through KMS or HSM.
- PCI DSS v4.0.1: 51 future-dated requirements became mandatory on 31 March 2025, as Bright Defense explains.
- Audit logging, environment segmentation and regular penetration testing.
How to Move from a Legacy Core to Modern Architecture
A legacy system rarely has to go in one weekend. A phased path, often combined with cloud migration, works better:
- Inventory systems, integrations and data dependencies.
- Choose a strategy: phased or side-car instead of big bang.
- Put an API layer on top of the legacy core to expose its capabilities.
- Move functions out gradually into new services: onboarding, payments, cards.
- Migrate data and run in parallel with reconciliation.
- Retire old components after validation.
How Dotcode Can Help
We start with discovery, then design an API-first, cloud-native architecture with security built in from the first sprint. Our experience covers integrations with legacy cores and payment systems; see our fintech integration services. For cloud work, our cloud solutions team takes it from there, and for the bigger picture our technology consulting helps choose the path.
After launch we stay on for support. You can see how this applies to the customer side on our mobile banking app development page, browse the fintech industry page, read client feedback on Clutch or return to the Dotcode homepage.
Final Thoughts
Platform architecture determines how fast a bank or fintech can launch products and connect partners. A modular, API-first approach on cloud-native infrastructure, with phased migration, carries less risk than replacing the core from scratch.
FAQ
What is digital banking platform architecture?
It is the structure of services, layers and integrations that delivers digital banking: channels, an API gateway, microservices, the core ledger, a data layer, security and links to external providers.
What are the main components of a digital banking platform?
Channels, API gateway and orchestration, core banking, customer onboarding, a payments hub, cards and wallets, data and analytics, security and IAM, and a notification service.
What is the difference between core banking and a digital banking platform?
Core banking handles accounting and product rules: accounts, the ledger and postings. The platform handles customer experience, process orchestration and integrations, and exposes the core through APIs.
Why use microservices architecture in banking?
Domains such as accounts, payments and cards deploy and scale separately, so releases are faster and failures stay contained. The price is distributed transactions and heavier observability and DevOps demands.
What does a cloud-native banking architecture look like?
Containers on Kubernetes with autoscaling, managed databases and queues, infrastructure as code, multi-AZ deployment, disaster recovery and monitoring, designed around data residency and DORA requirements.
How do you migrate from a legacy core to a modern banking architecture?
In phases: inventory what you have, expose the core through an API layer, move functions into new services one by one, run in parallel with reconciliation and retire old components after validation.